What Do Budget 2027's Business Tax Measures Mean for Malaysia Companies?
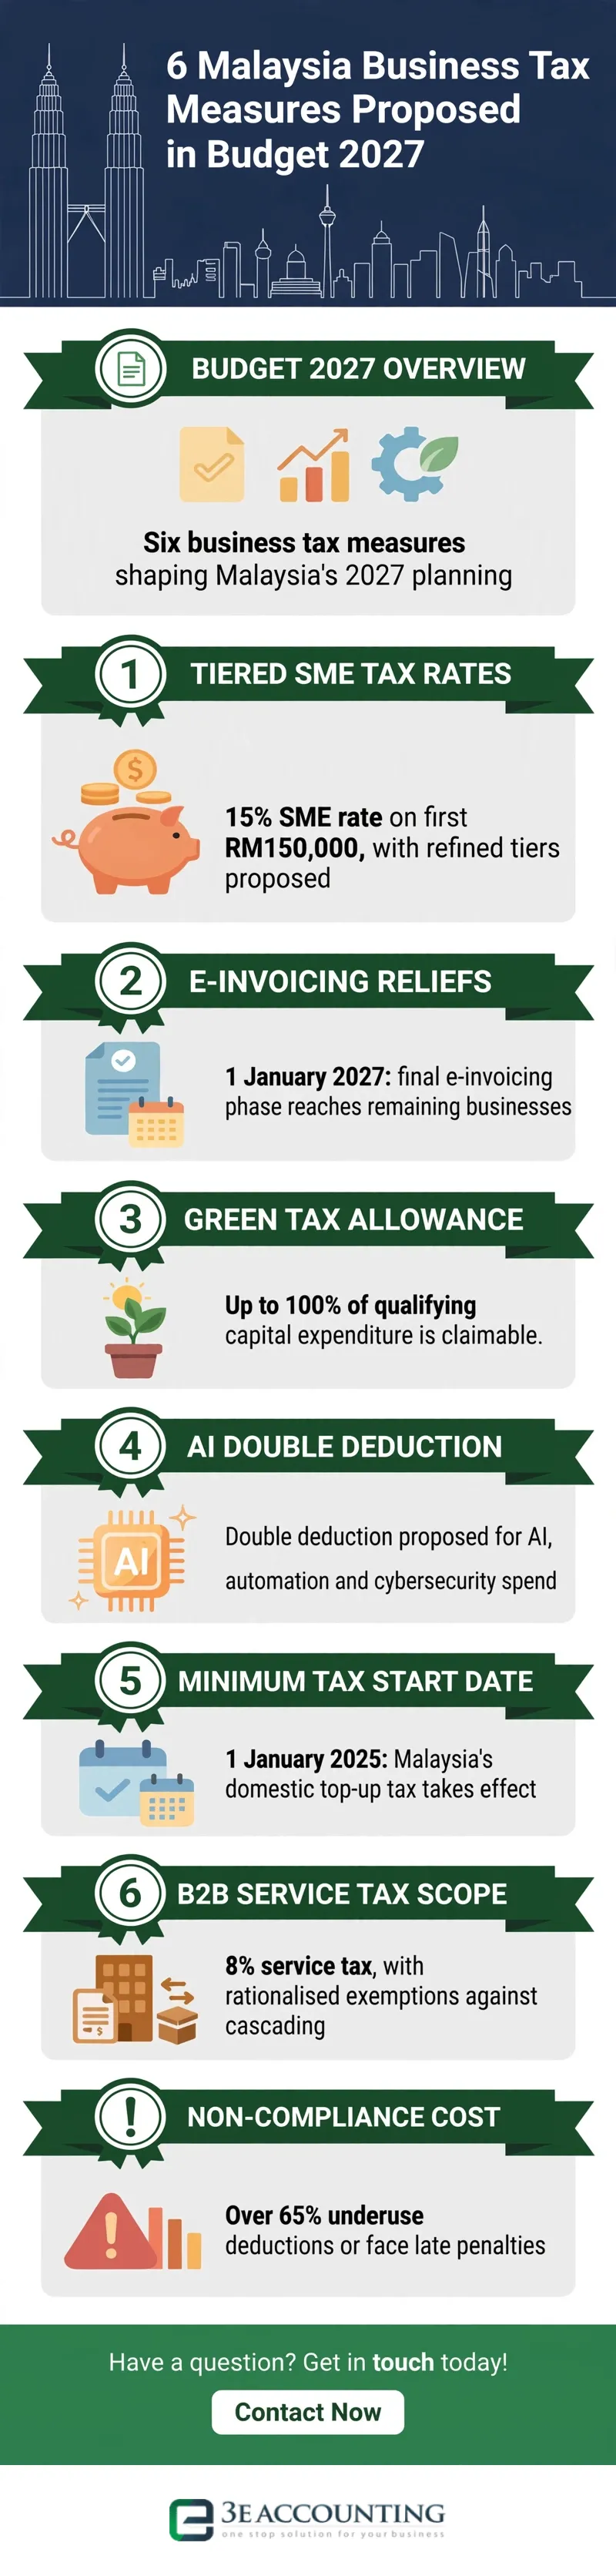
How could changes in Malaysia's business tax rules affect your company's plans? Malaysia's Budget 2027 includes SME rate cuts and green incentives, while some related ideas remain unconfirmed. In this blog, we examine six business tax planning topics, distinguishing proposals from existing rules and illustrative ideas. Contact our team to review your current setup.
How Will Tiered SME Corporate Income Tax Rates Change?
Qualifying SMEs currently pay 15% corporate income tax on their first RM150,000 of chargeable income, 17% on the band up to RM600,000 and 24% above that. Budget 2027 proposes reducing the first two rates to 14% and 16% respectively from the 2027 assessment year. We help clients model the proposed bands against current chargeable income before year-end decisions.
Current SME corporate income tax bands before the proposed 2027 changes
| Chargeable income band | Current rate for qualifying SMEs |
|---|---|
| First RM150,000 | 15% |
| RM150,001 to RM600,000 | 17% |
| Above RM600,000 | 24% |
Are Expanded E-Invoicing Tax Reliefs Available?
Under LHDN's phased rollout, the implementation date for taxpayers with annual turnover or revenue up to RM5 million was 1 January 2026. LHDN's updated timeline exempts taxpayers below RM3 million, subject to the applicable guidance. The Budget 2027 tax measures do not list a new dedicated e-invoicing relief; accelerated allowances or deductions for these compliance costs should not be assumed without confirming eligibility. We help clients review their adoption timeline and eligible expenditure.
How Does the Green Investment Tax Allowance Work in Malaysia?
Malaysia allows qualifying green projects to claim up to 100% of qualifying capital expenditure under the Green Investment Tax Allowance. Budget 2027 proposes revised Green Investment Tax Allowance tiers, with allowances of up to 100% for certain qualifying projects and assets. Eligibility, income offsets and effective dates differ by category, so companies should check the specific conditions before committing to a project. We help clients review certification and asset-purchase requirements.
AI and Automation Deductions
31 December 2030 is the proposed end date for accelerated capital allowances on qualifying information and communications technology (ICT) equipment and software expenditure. A dedicated double deduction for AI, automation and cybersecurity spending is an illustrative idea, not a measure identified in the Budget 2027 tax measures. Eligibility depends on the expenditure and applicable conditions. We help clients review and document potential claims.
Global Minimum Tax
Malaysia's Qualified Domestic Minimum Top-Up Tax applies for financial years beginning on or after 1 January 2025. The global minimum tax generally covers groups with consolidated revenue of at least EUR750 million in at least two of the four preceding financial years. A Budget 2027 refinement to the domestic top-up rules is not identified in the published tax measures. We work with multinational companies in Malaysia to review group structures, substance and data readiness.
B2B Service Tax Scope
Malaysia's service tax on most taxable services has stood at 8% since 1 March 2024. Where taxed services feed other taxed services, costs can cascade down the supply chain. New B2B exemptions aimed at preventing this are an illustrative idea, not a measure identified in the Budget 2027 tax measures. We review service contracts and applicable existing exemptions to flag exposures.
The High Cost of Non-Compliance
Over 65% of companies underuse eligible deductions or face late penalties. Missing a filing deadline or overlooking an eligible deduction can increase a company's tax costs. A structured annual review can help businesses track their obligations and support their claims.
Ready to Plan for Budget 2027?
Tell us your business profile and we will map the proposed measures to your tax position.
Frequently Asked Questions
Effective dates vary by measure. The proposed SME rate changes are intended to apply from the 2027 assessment year, while other measures have different dates. Check the relevant legislation and guidance before applying a proposal.
The Budget 2027 tax measures do not list a new dedicated e-invoicing relief. LHDN's updated timeline exempts taxpayers with annual turnover or revenue below RM3 million, subject to the applicable guidance. Check eligibility before assuming any costs qualify for a deduction.
Ordinary SMEs that are not part of a group meeting the threshold are generally outside its scope. The global minimum tax generally applies to groups with consolidated revenue of at least EUR750 million in at least two of the four preceding financial years.
A dedicated AI double deduction is an illustrative idea, not a measure identified in the Budget 2027 tax measures. The proposed extension of accelerated capital allowances for qualifying ICT equipment and software has its own eligibility conditions.
We help clients model proposed rates against current chargeable income, structure qualifying claims and align e-invoicing timelines with assessment years. Reach us through our contact page to map the measures to your business.
Abigail Yu
Director
Abigail Yu oversees executive leadership at 3E Accounting Group, leading operations, IT solutions, public relations, and digital marketing to drive business success. She holds an honors degree in Communication and New Media from the National University of Singapore and is highly skilled in crisis management, financial communication, and corporate communications.